余剑峰,男,毕业于宾夕法尼亚大学沃顿商学院,现任清华大学五道口金融学院建树金融学讲席教授,清华大学国家金融研究院资产管理研究中心主任。
本页面主要目录有关于余剑峰的:人物经历、主要成就等介绍

余剑峰,男,毕业于宾夕法尼亚大学沃顿商学院,现任清华大学五道口金融学院建树金融学讲席教授,清华大学国家金融研究院资产管理研究中心主任。
本页面主要目录有关于余剑峰的:人物经历、主要成就等介绍
余剑峰
中华人民共和国
男
汉
金融学
金融
教师
清华大学五道口金融学院建树金融学讲席教授
教授
主要从事行为金融和宏观金融的理论和实证研究。
时间 | 院校 | 专业 | 学位 |
xx--2000 | 中国科学技术大学 | 概率统计 | 学士 |
耶鲁大学 | 统计 | 硕士 | |
xx--2008 | 宾夕法尼亚大学沃顿商学院 | 金融系 | 博士 |
2008-2016,明尼苏达大学,卡尔森管理学院,金融学,助理教授,副教授(终身教授),正教授,Piper Jaffray讲席教授。
2015-2016,香港中文大学(深圳)经管学院,金融学教授,执行副院长。
2016-至今,清华大学五道口金融学院,建树金融学讲席教授。
研究领域
行为金融学
量化投资策略
市场摩擦中的资产定价
国际市场
基于经济周期模型的资产定价
论文
[1]Investor Sentiment and the Mean-Variance Relation, (with Yu Yuan), Journal of Financial Economics100, May 2011, pp. 367-281
[2]The Short of It: Investor Sentiment and Anomalies (with Rob Stambaugh, and Yu Yuan), Journal of Financial Economics104, May 2012, pp. 288-302
·Inaugural AQR Insight Award, honorable mention, 2012
·RWC Marshall Blume Prize, honorable mention, 2011
[3]Investor Attention, Psychological Anchors, and Stock Return Predictability (with Jun Li), Journal of Financial Economics104, May 2012, pp. 401-419
[4]Using Long-Run Consumption-Return Correlations to Test Asset Pricing Models, Review of Economic Dynamics15, July 2012, pp. 317-335
[5]Technological Growth and Asset Pricing, (with Nicolae Garleanu and Stavros Panageas), Journal of Finance67, August 2012, pp. 1265-1292
·Smith-Breeden Prize (First Prize), 2012
[6]Government Investment and the Stock Market (with Frederico Belo), Journal of Monetary Economics60, April 2013, pp. 325-339
[7]A Sentiment-based Explanation of the Forward Premium Puzzle, Journal of Monetary Economics60, May 2013, pp.474-491
[8]Uncertainty, Risk, and Incentives: Theory and Evidence, (with Zhiguo He, Si Li and Bin Wei), Management Science60, January 2014, pp. 206-226
·3rd Annual TCFA Best Paper Award, 2012
[9]The Long of It: Odds That Investor Sentiment Spuriously Predicts Anomaly Returns, (with Rob Stambaugh and Yu Yuan), February 2014, Journal of Financial Economics114, December 2014, pp. 613-619
[10]Financial Entanglement: A Theory of Incomplete Integration, Leverage, Crashes, and Contagion (with Nicolae Garleanu and Stavros Panageas), July 2015, American Economic Review105, pp. 1979-2010
[11]Arbitrage Asymmetry and the Idiosyncratic Volatility Puzzle (with Rob Stambaugh and Yu Yuan), October 2015, Journal of Finance70, pp. 1903- 1948
[12]Asset Pricing in Production Economies with Extrapolative Expectations (with David Hirshleifer and Jun Li), November 2015, Journal of Monetary Economics76, pp. 87-106
[13]Short- and Long-Run Business Conditions and Expected Returns (with Qi Liu, Libin Tao and Weixin Wu), Management Science, forthcoming
[14]Reference-Dependent Preferences and the Risk-Return Trade-off (with Huijun Wang and Jinghua Yan), Journal of Financial Economics, forthcoming
·Q-Group Research Award, 2012
·Chicago Quantitative Alliance Academic Competition, Third Prize, 2014
[15]Investor Sentiment and Economic Forces (with Junyan Shen), December 2013, Journal of Monetary Economics86, pp.1‐21, Lead Article
·Chicago Quantitative Alliance Academic Competition, First Prize, 2012
·Crowell Memorial Prize (Third Prize), PanAgora Asset Management, 2013
·TCFA Best Paper Award, 2013
[16]Optimal Long-Term Contracting with Learning, (with Zhiguo He, Bin Wei, and Feng Gao), October 2015, Review of Financial Studies30, pp. 2006‐2065
[1].Impediments to Financial Trade: Theory and Applications (with Nicolae Garleanu andStavros Panageas), September 2017
[2].Lottery‐Related Anomalies: The Role of Reference‐Dependent Preferences (with LiAn, Huijun Wang, and Jian Wang), November 2017
·CQAsia Academic Competition, First Prize, 2016
[3].Drifting Apart: The Pricing of Assets when the Benefits of Growth are not SharedEqually (with Nicolae Garleanu, Stavros Panageas, and Dimitris Papanikolaou),August 2015
[4].Time‐Varying Demand for Lottery: Speculation Ahead of Earning Announcements(with Bibo Liu, Huijun Wang and Shen Zhao), September 2017
[5].Aggregate Expected Investment Growth and Stock Market Returns (joint with Jun Liand Huijun Wang), March 2018
[6].Characteristics‐Based Factors (with Zhuo Chen, Bibo Liu, Huijun Wang, ZhengweiWang), January 2018
新亚洲娱乐(英文名:ASIA ENTERTAINMENT GROUP LIMITED,全称:新亚洲娱乐联盟集团有限公司)是一家以从事戏剧制作人及杂项戏剧服务为主的企业,成立于1999年,位于香港特别行政区。旗下分公司包括虎威艺能创作有限公司(TGS HK)、稻草人娱乐创作社(Scarecrow Entertainment)、虎威王朝音乐创作股份有限公司(TGS Music)、虎威活力娱乐传播有限公司(TGS Taiwan)、AK Entertainment(Korea)以及AEG Korea等。
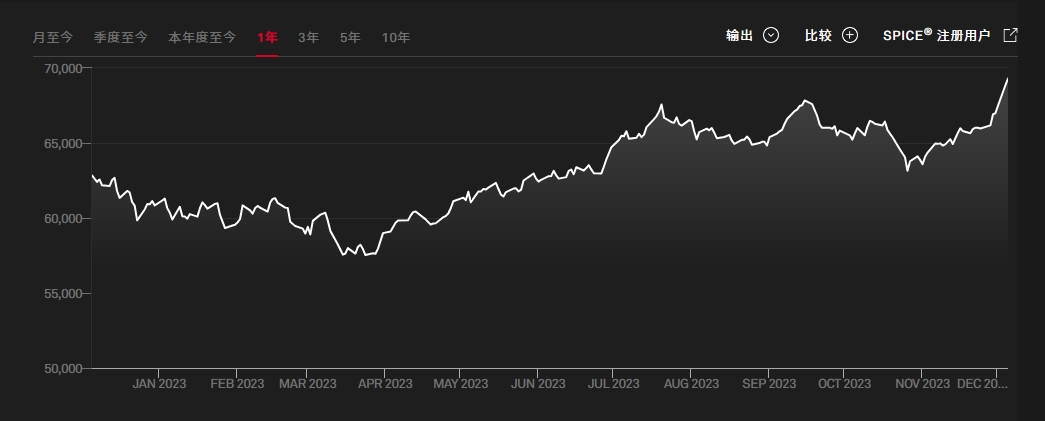
印度孟买SENSEX30指数(又称孟买敏感指数)为印度最被广泛使用的指数,为投资印度的重要参考指标,是由孟买证券交易所发行。由于各类媒体提到的“印度股市”,实际上都是孟买股票交易所,因此,该交易所的SENSEX-30指数几乎成了印度股市的代名词。